
Imagine owning a slice of an office building, a government bond or a private credit fund as easily as holding a stock — tradable in minutes, divisible into tiny fractions, settled almost instantly. That is the promise of tokenization: representing real-world assets as tokens on a blockchain. After years of conference hype, the idea has entered a serious phase, with major banks, asset managers and exchanges running live pilots involving billions in tokenized funds and bonds.
What Tokenization Actually Changes
The token itself is the simple part; the plumbing is the innovation. A tokenized asset carries its ownership record, transfer rules and compliance checks in programmable form, allowing settlement that today takes days of intermediary reconciliation to finish in minutes. Fractionalisation opens assets long restricted to institutions — private equity, real estate, infrastructure — to smaller investors, while 24-hour markets erase the waiting imposed by exchange hours. Analyses from Forbes Digital Assets project the market could reach trillions within the decade if regulation and infrastructure mature together.
Our crypto coverage distinguishes this institutional wave from the speculative token booms that preceded it. The buyers here are treasurers and fund managers testing efficiency, not traders chasing memes — which makes progress slower, duller and far more likely to endure. Tokenized money-market funds, usable as collateral while still earning yield, have emerged as the first genuinely popular product.
The Hard Problems Are Legal, Not Technical
A token is only as good as the legal claim behind it. If the issuer fails, does the token holder own the asset or merely a promise? Jurisdictions answer differently, and harmonising those answers is the industry’s real bottleneck. Custody, identity verification, and interoperability between competing blockchains add further friction, themes regulators discussing frameworks with bodies such as the IMF return to consistently.
The sober forecast is evolution, not explosion: back offices first, then funds and bonds, with property and private markets later. Tokenization will not make bad assets good or remove the need for due diligence. But by making ownership cheaper to divide, transfer and audit, it could widen who gets to own productive assets — and that, if it happens, is a change worth more than the technology that enabled it.
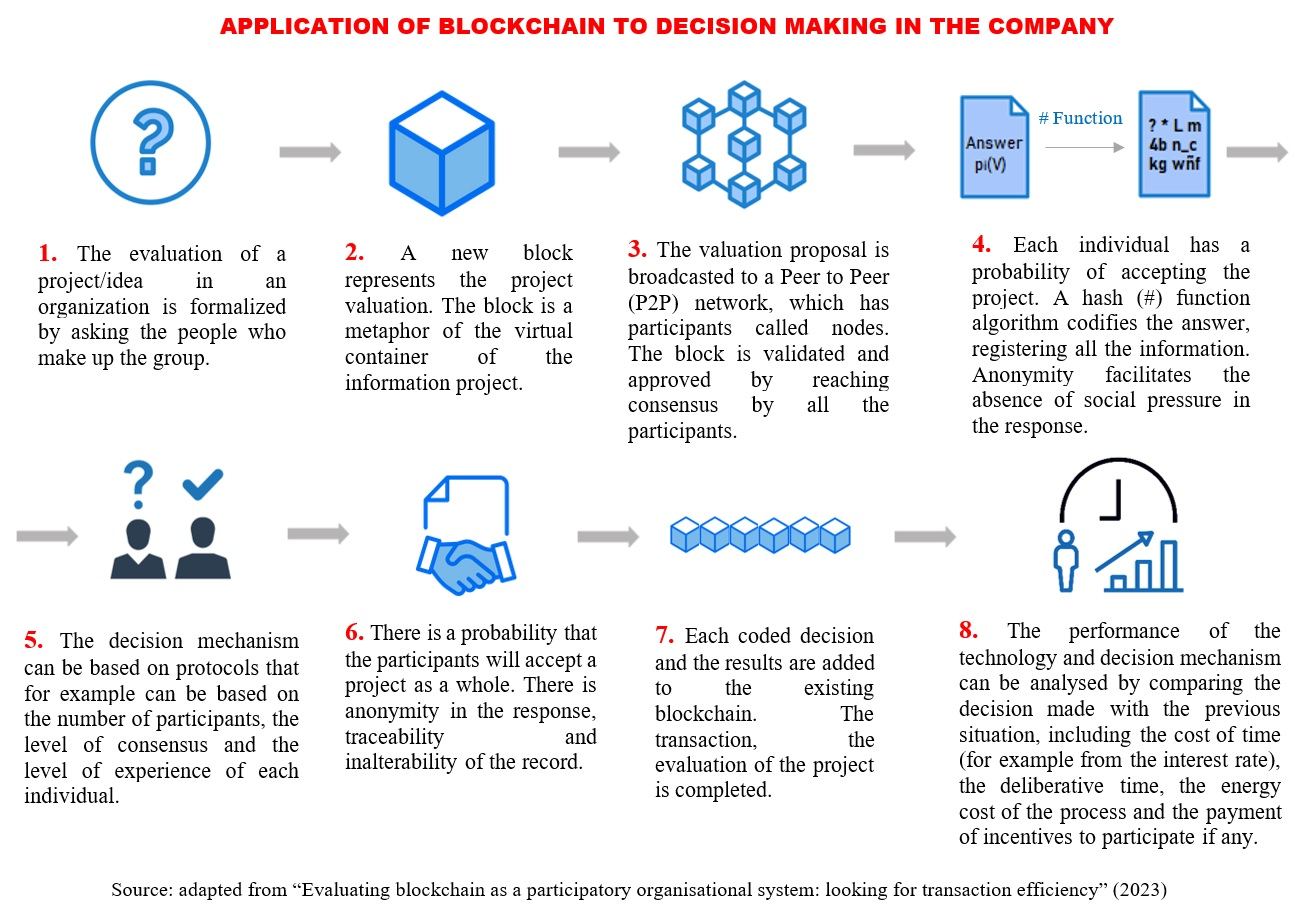
Sceptics ask a fair question: if the asset, the law and the custodian remain off-chain, what has the blockchain actually added? The industry’s best answer is shared infrastructure. Today every intermediary keeps its own ledger and reconciles with everyone else’s, expensively and slowly; a common token standard lets those parties transact against one record with rules enforced by code. Whether that efficiency justifies rebuilding market plumbing is an empirical question the pilots are designed to answer with data rather than evangelism. If the savings prove real at scale, adoption will follow the path of every successful financial technology: invisibly, through the back office, until one day it is simply how things settle.
Watch the pilots, read the legal structures carefully, and judge each product on its claim rather than its technology when deciding anything.
